Iran Strait of Hormuz Blockade 2026: Full Breakdown of the Oil Crisis, Global Shipping Disruptions, and What's Next
Published
Iran Strait of Hormuz Blockade 2026: Full Breakdown of the Oil Crisis, Global Shipping Disruptions, and What’s Next
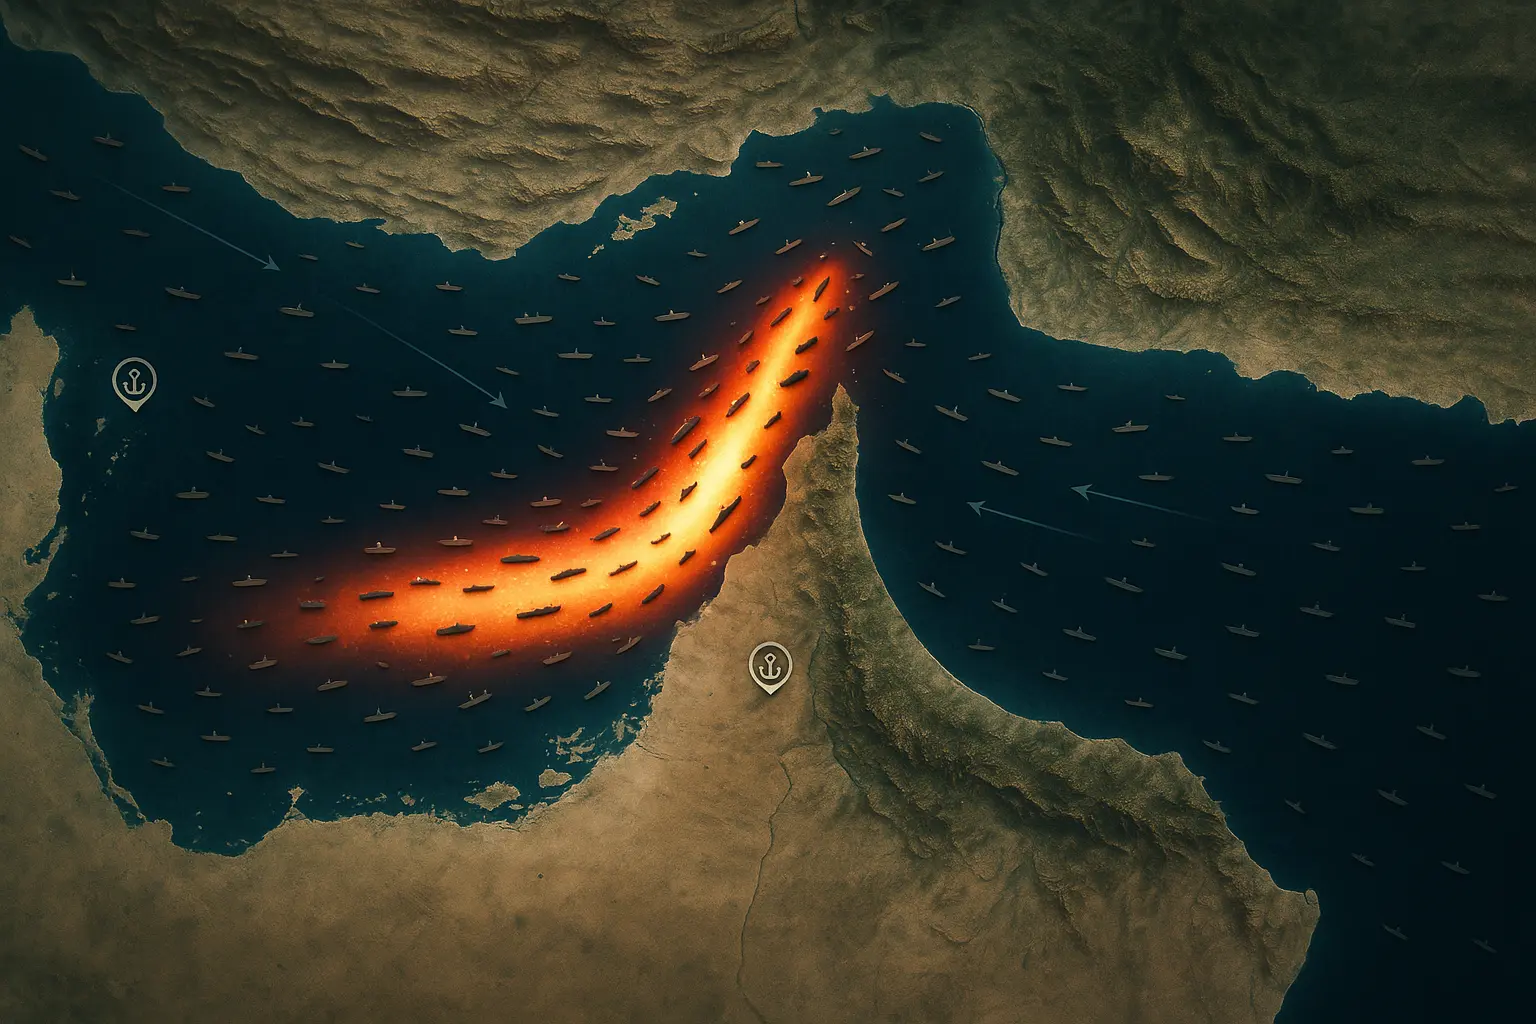
A map makes the Strait of Hormuz look manageable. Then you pull up vessel traffic and remember how absurd the whole setup is: roughly 21 million barrels a day, plus LNG and everything else, all funneled through a waterway that the global economy has spent years pretending is just… there. Reliable by default. Normal.
It never really was.
As of June 2025, that chokepoint is effectively closed.
What makes this hard to explain in TV-segment terms is that it isn’t only about missiles, naval patrols, or leaders making threats. It’s also tanker routing, insurance exclusions, refinery scheduling, LNG contracts, fertilizer shipments, and a lot of tedious operational stuff that usually gets ignored right up until it breaks. Then suddenly it shows up in places people do notice: freight bills, food prices, airline surcharges.
I’ve spent fifteen years looking at energy logistics and maritime risk, and this one feels unusually visible. You can literally watch the traffic thin out. You can see insurers start backing away. You can see the market repricing multiple commodities at the same time, which is never a comforting sight.
The headline version is simple: ships stopped moving. The real version is messier. How the escalation unfolded matters. So does the difference between flows that are fully stuck and flows that can still limp through. The “other routes” people always mention mostly don’t solve much. And insurance—boring, yes—is doing more to freeze commerce than half the military commentary on cable news.
The Timeline: How We Got Here
This didn’t begin with one clean, cinematic event. Looking back, it was a chain of moves that kept shrinking the room for de-escalation.
January: the sanctions escalation
After back-channel nuclear talks collapsed in late 2024, the Trump administration expanded sanctions on Iran’s petroleum sector in January 2025. The key change wasn’t just broader sanctions on paper. It was the secondary sanctions aimed at anyone helping move Iranian oil, insurers included. Once insurers are part of the target set, the problem stops being abstract very quickly.
March: the shipping incidents
Between March 3 and March 17, three merchant vessels reported mine damage in the Gulf of Oman risk zone. Two of the mines were identified as Iranian-manufactured EM-52 bottom mines, according to reporting that circulated in maritime security channels at the time. Around then, the IRGC warned that vessels carrying what it called “sanctioned goods” would face “natural consequences” in Gulf shipping lanes. That kind of language tends to sound theatrical until underwriters start recalculating exposure.
April: the insurance break
This was the point, at least to me, where the crisis stopped being mainly geopolitical and became operational. Lloyd’s syndicates pushed war-risk premiums for Hormuz transits from roughly 0.5% of hull value to above 7%. Depending on vessel value and cargo, that can add something like $15-25 million to a loaded VLCC voyage. A few major shipping companies just suspended operations. Understandably.
May: the blockade
On May 12, the US announced a naval blockade of Iranian ports, though it was described as “enhanced sanctions enforcement” rather than a formal blockade. Lawyers care about that distinction for good reason. Iran responded by declaring the Strait a war zone and adding fast-attack craft, drones, and mines to the picture.
There isn’t a literal gate across the Strait. But between mine threats, confirmed sea mines in the area, suspended insurance cover, and declared military zones, commercial traffic is down 89% from January levels. If you’re a shipowner, that’s closed enough.
One practical note here: AIS data is often more useful than speeches. MarineTraffic and VesselFinder will usually tell you more about what is actually happening than a press briefing will. I check that before I check half the commentary, honestly.
What’s Actually Blocked: Beyond the Barrel
A lot of coverage still treats this as an oil story, full stop. That’s too tidy.
The Strait of Hormuz typically handles about:
- 21 million barrels per day of crude and condensate
- 3.5 billion cubic feet per day of LNG, roughly a quarter of global LNG trade by some estimates
- and then all the less glamorous stuff people forget until prices move: refined products, petrochemicals, fertilizer feedstocks
Those secondary flows are not side notes.
Crude oil and condensate
Saudi Arabia, Iraq, the UAE, Kuwait, and Iran together move around 17-18 million barrels a day through Hormuz. The remaining 3-4 million barrels come from Qatar and smaller producers.
LNG
Qatar alone accounts for about 20% of global LNG trade, and nearly all of that goes through Hormuz. Europe is exposed because it leaned much harder on Qatari LNG after cutting Russian gas supply. Japan, South Korea, and Taiwan are all vulnerable too, for slightly different reasons.
The part people keep underplaying: fertilizers and petrochemicals
The Gulf produces roughly 15% of global urea and ammonia exports. That’s fertilizer input, not some obscure commodity line buried in a spreadsheet. Saudi Arabia’s SABIC and Qatar’s QAFCO are major suppliers into Asian and African markets. If those flows stay constrained, food production costs keep climbing even after the first oil panic cools off.
And yes, this is where some TV coverage becomes almost useless. Everything gets flattened into “oil up, markets nervous,” as if the story ends at crude benchmarks. It doesn’t.
Refined products
Kuwait’s Mina al-Ahmadi refinery and Saudi Arabia’s Ras Tanura facility export gasoline, diesel, and jet fuel across Asia. Disruptions here can hit faster than crude disruptions because consumers and airlines buy finished products, not upstream barrels.
So when the headlines fixate on Brent and WTI, it’s worth remembering that LNG, fertilizers, and refined products are tied up in the same bottleneck. The grocery bill effect isn’t some mysterious second-order inflation problem. It’s part of the same supply chain shock.
Also, if you’re watching markets, don’t just stare at Brent. The JKM Asian LNG benchmark has tripled since January, and urea/ammonia futures are a pretty good clue about where food-cost pressure may show up next.
The Bypass Myth: Why Alternative Routes Can’t Save Us
Every time Hormuz risk spikes, someone says there are other routes.
Well, yes. Sort of. Not enough of them.
Saudi East-West Pipeline (Petroline)
This line runs 746 miles from Abqaiq to Yanbu on the Red Sea. Nameplate capacity is 5 million barrels per day. Real usable capacity looks closer to 2-3 million bpd right now, and Saudi Arabia needs part of that for its own Red Sea refinery system. So net bypass capacity is maybe 2 million bpd.
UAE Fujairah bypass pipeline (ADCOP)
The Abu Dhabi Crude Oil Pipeline moves oil from Habshan to Fujairah, outside Hormuz. Capacity is 1.5 million bpd. It’s useful. It’s also been running near capacity for months, so there isn’t much extra room.
Iraq-Turkey Pipeline (Kirkuk-Ceyhan)
In theory this could add 500,000-900,000 bpd. In practice it has been unreliable because of Baghdad-KRG disputes. And even if it ran perfectly, it only really helps Iraq.
Then you run into the basic math.
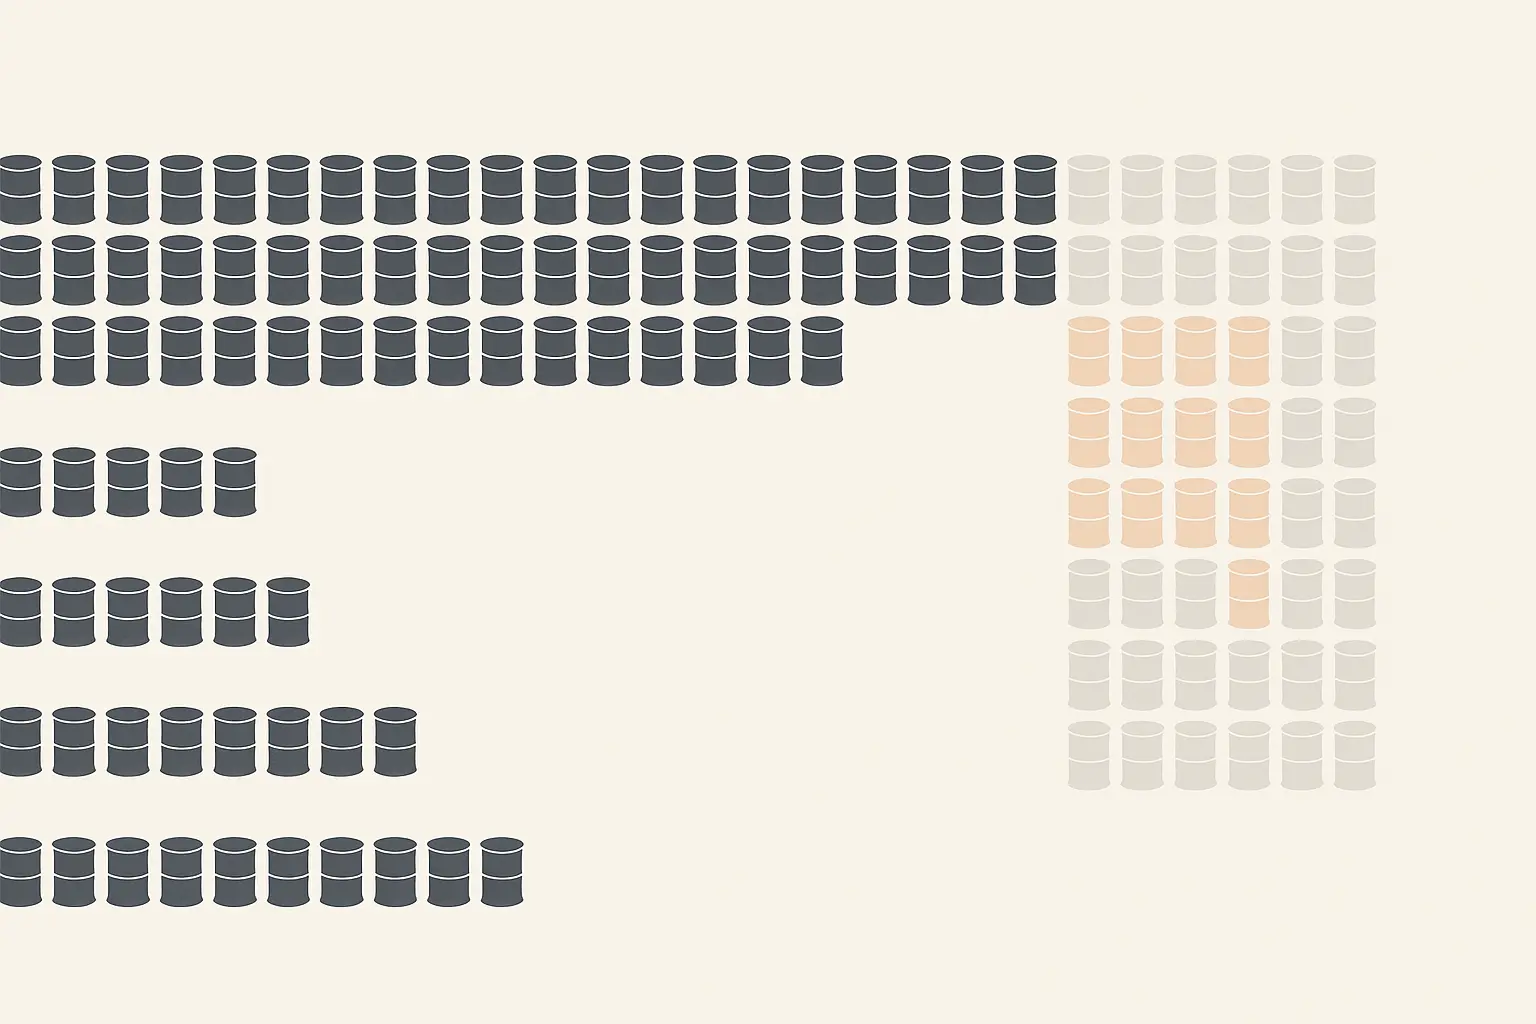
Pre-crisis Hormuz flow: about 21 million bpd.
Optimistic bypass capacity: around 4-5 million bpd.
Shortfall: 16-17 million bpd.
That’s the whole problem in three lines.
There is no infrastructure workaround for a Hormuz closure at current demand levels. The remaining tools are uglier: strategic reserve releases, more production from non-Gulf suppliers, and demand destruction—which is the polite term for recession, rationing by price, or both.
There is also a tanker fleet issue that gets skipped over too often. Even if bypass capacity were larger, ships are configured around specific routes and loading patterns. VLCCs loading at Ras Tanura can’t just be dropped into any alternative chain without friction. Some can’t transit the Suez Canal fully loaded. Rerouting creates congestion, timing issues, and its own freight spike. Tanker rates for the vessels still moving through the region are up roughly 400% since January.
The Insurance Crisis: Why Risk Pricing Is the Real Blockade
If I had to pick the least interesting-sounding but most important part of this crisis, it would be insurance.
Ships don’t move without it. That’s not a metaphor.
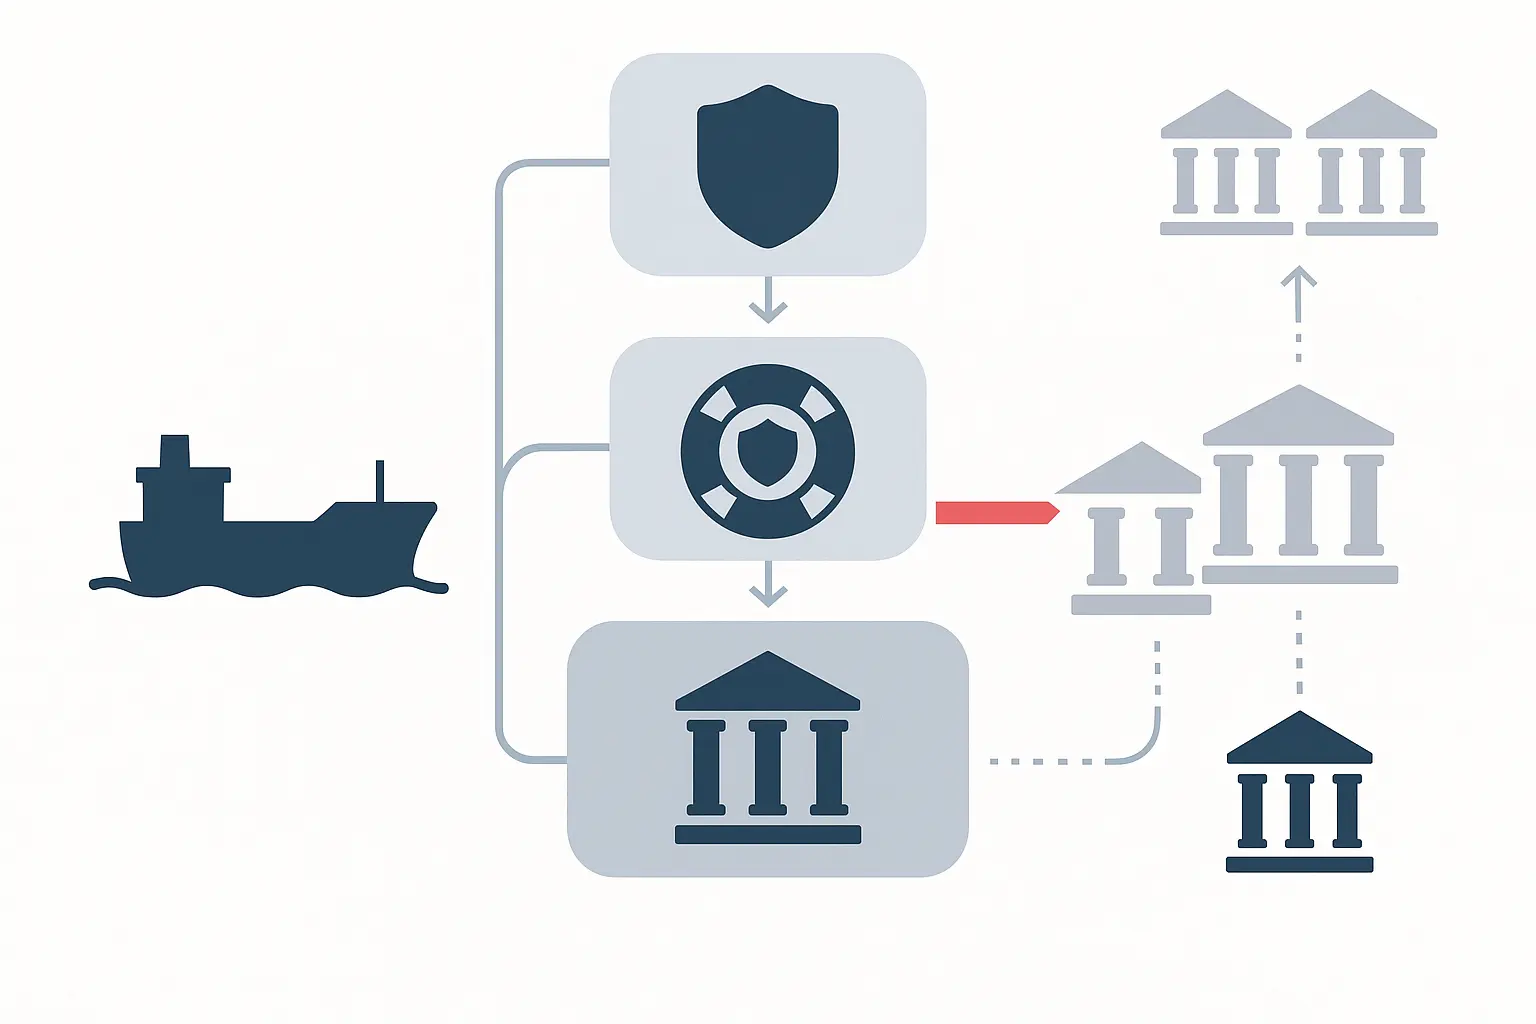
War-risk premiums
Standard marine policies exclude war, terrorism, and mines. So shipowners buy separate war-risk cover, usually priced as a percentage of hull value. A VLCC worth $120 million paying a 7% premium is looking at another $8.4 million per voyage just for that layer.
P&I clubs
Protection and Indemnity clubs cover liability, pollution, crew injury, and the rest of the expensive mess that follows when shipping goes wrong. Several clubs have carved Hormuz transits out of standard cover, forcing owners into standalone policies at painful rates.
Reinsurance
The primary insurers aren’t the whole story. Behind them sit reinsurers like Munich Re, Swiss Re, and Hannover Re. They set the real capacity ceiling. In April, most major reinsurers pulled war-risk capacity for Hormuz transits entirely. Once that happens, primary insurers either stop writing the business or keep risk on their own books in amounts they generally do not want.
That’s why some military commentary misses the point. Even if a shipowner is willing to take the chance, lenders typically require insurance, charterers require insurance, and counterparties require insurance. No cover, no voyage.
So yes, the naval threat is real. But the insurance market is what actually froze commerce.
If you’re following this professionally, Lloyd’s List is still worth the money. Argus Media too, especially for tanker rates. I don’t enjoy recommending expensive subscriptions, and some industry intelligence products are wildly overpriced, but those two are usually better than the breathless nonsense that gets passed around for free.
Who’s Exposed: The Country Vulnerability Scorecard
The effects are not evenly distributed.
Tier 1: critical exposure
- Japan: More than 90% of crude imports move through Hormuz. Strategic reserves cover roughly 150 days, but a modern industrial economy starts feeling stress long before the reserve clock hits zero.
- South Korea: More than 70% Hormuz dependency, limited substitutes, and a petrochemical sector that really does not tolerate supply interruptions well.
- Taiwan: Very high LNG exposure. Without Qatari gas, rolling blackouts become a real possibility within 30-45 days.
Tier 2: severe exposure
- India: Roughly 60% Hormuz dependency. It has more domestic production and refining capacity than some peers, which helps a bit, not enough. It’s already negotiating emergency supply deals with Russia.
- China: Around 40% direct Hormuz exposure because its supplier base is more diversified—Russia, Brazil, West Africa. Even so, China, India, Japan, and South Korea account for most of the demand behind Hormuz traffic. Chinese refiners have also been quietly building inventories for months.
Tier 3: manageable, but still bad
- European Union: Lower direct oil exposure, about 20% of imports, but serious LNG vulnerability after the loss of Russian supply. Prices are already up more than 300%.
- United States: Net energy exporter, yes, but that doesn’t mean immunity. Global oil prices still feed into domestic fuel prices and inflation. Oil-driven inflation is already running 2-3% above baseline.
On the exporter side, Gulf producers are exposed too. Saudi Arabia can reroute some crude through Yanbu. Iraq and Kuwait have very few alternatives. Iran, already constrained by sanctions, is now dealing with a US blockade of Iranian ports that has effectively wiped out what remained of its export capacity.
This is the part people miss when they ask why countries with no direct Hormuz imports should care. Because oil is globally priced. You do not need direct exposure to inherit the price shock.
Scenario Planning: What Happens Next
I don’t love pretending this can be forecast cleanly, and I might be wrong about the weighting here, but this is how I’d think about it right now.
Scenario 1: negotiated partial reopening (35%)
This probably looks like a UN- or GCC-backed maritime corridor with naval escort, enough to restore reduced but meaningful traffic—maybe 8-12 million bpd—within 60-90 days.
What I’d watch:
- China putting real pressure on both sides, not just issuing vague statements about restraint
- signals from IRGC leadership that civilian shipping may be treated differently from military-linked traffic
Market impact: Brent settles somewhere in the $150-170 range. LNG stays expensive, but not completely unmanageable.
Scenario 2: prolonged disruption (45%)
Unfortunately, this feels like the most plausible one. Current conditions drag on for 6-12 months. Mine-clearing slowly opens safer zones. Insurance markets adapt a bit, possibly with state-backed facilities stepping in.
Things I’d watch here are less dramatic: no major military escalation, continued strategic petroleum reserve releases, and recessionary demand destruction easing some pressure by brute force rather than policy design.
Market impact: Brent bouncing between $180 and $220. A global fuel crisis pushes energy-intensive economies into recession. At that point, “what happens if the Strait of Hormuz closes?” stops being a hypothetical and becomes the working assumption.
Scenario 3: wider escalation (20%)
This is the ugly one. Direct US-Iran confrontation, Iranian strikes on Saudi or UAE production sites, missile exchanges across the Gulf.
Potential triggers:
- US blockade enforcement intercepting a Chinese-flagged vessel
- IRGC anti-ship missile use against non-Iranian targets
- expanded Israeli strikes on Iranian nuclear facilities
Market impact: Brent briefly above $300. At that point demand destruction isn’t really market-led anymore; it’s imposed by sheer price shock and physical scarcity. People will reach for 1970s oil-shock comparisons, and for once that comparison would not be lazy.
Most likely, this doesn’t resolve neatly and it doesn’t instantly tip into all-out war either. It just drags. Grinds, really. That’s the scenario I’d plan around.
Practical Actions: What to Do Now
A few things I’d actually do. Not “10 hacks to protect your portfolio.” Just practical stuff.
This week
Look at energy exposure more broadly than gasoline. Electricity source mix matters. Heating matters. Food costs matter because fertilizer and transport are embedded in them. If you run a business with any shipping dependence, ask your logistics providers exactly what routes have changed and what surcharges are already being added. If they answer in vague corporate mush, ask again.
This month
If you can hedge, hedge. For businesses, that usually means fixed-price energy contracts where available. For households, maybe it means buying heating fuel earlier than usual if you’re in the Northern Hemisphere, or booking flights before jet fuel surcharges fully work through the system. I usually hate “buy now” advice because it so often turns into panic-buying with better branding, but earlier pricing may genuinely be better than later pricing here.
Ongoing
Track shipping and insurance, not just diplomatic statements. If this is part of your job, data from Lloyd’s List Intelligence, Argus Media, and Platts is useful. If it isn’t, weekly EIA petroleum status reports and IEA monthly oil market reports are still solid anchors.
Where This Is Heading
Even after some eventual resolution, this is likely to reshape energy security planning for years.
A few things probably stick:
- more Gulf export diversification infrastructure
- faster buildout of LNG import terminals in Asia
- larger and more actively managed strategic reserves
- a permanently heavier naval presence in the Gulf
For deeper analysis, CSIS and Columbia University’s Center on Global Energy Policy are both worth following. The EIA’s Strait of Hormuz fact sheet is still one of the better baseline references to keep bookmarked.
The question I keep landing on is less “when does this end?” and more: what does resilience actually look like when your household, your company, or your country has spent years assuming cheap, uninterrupted transit through a tiny chokepoint?
That assumption is gone now.
Last updated: June 2025. Situation evolving; check primary sources for the latest.
Worth sharing?
Send this to someone who would find it useful.